Carbon Black Weekly: Squeezed from Both Sides, Carbon Black Lingers at Low Levels(Oct 29)
Carbon Black Weekly: Squeezed from Both Sides, Carbon Black Lingers at Low Levels
1.1 Carbon Black Market Price Analysis
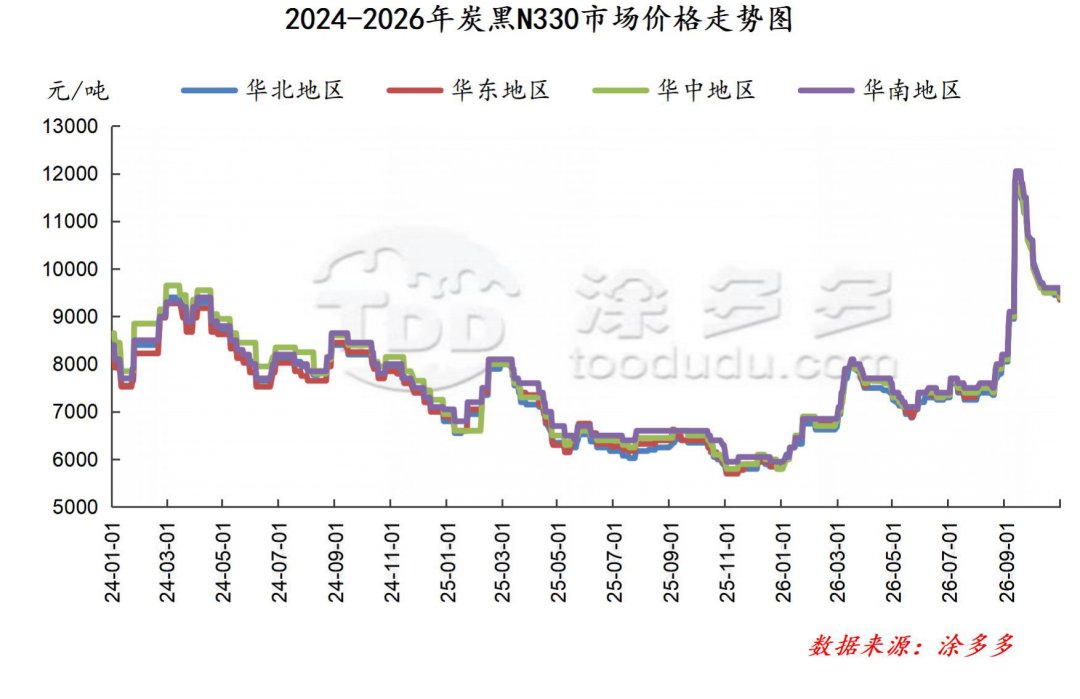
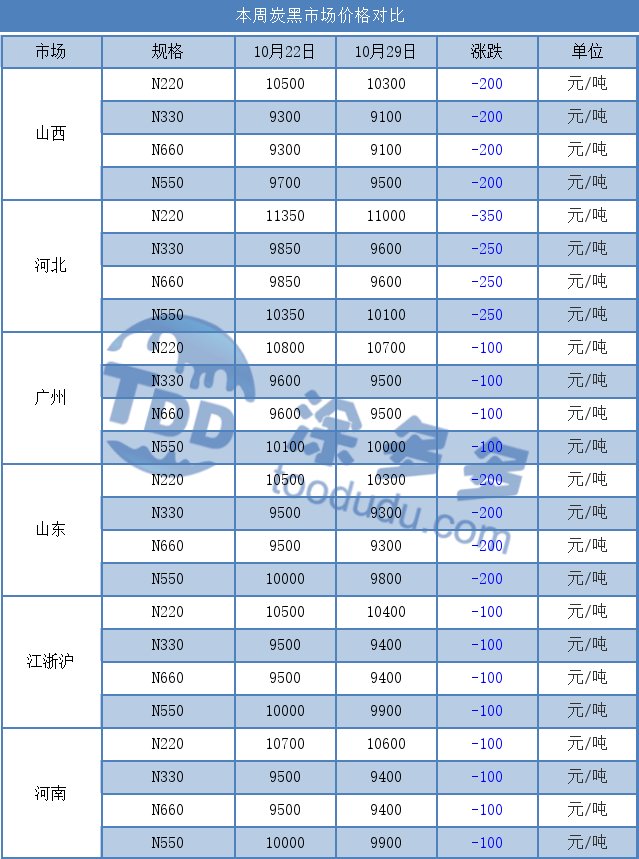
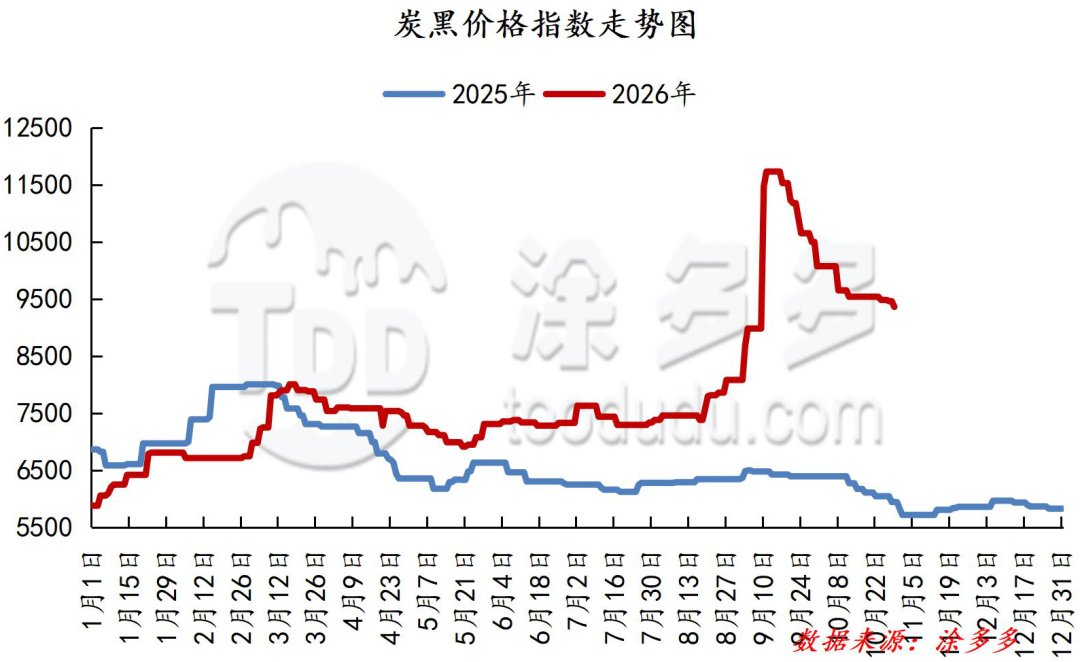
This week, domestic carbon black prices maintained a narrow declining trend. As of Thursday: Shandong region at 9,300 yuan/ton; Shanxi region at 9,100 yuan/ton; Hebei region at 9,600 yuan/ton; Guangzhou region at 9,500 yuan/ton; Zhejiang region at 9,400 yuan/ton. The domestic carbon black market maintained a weak state in new order negotiations, with significant negotiation pressure and most transactions remaining at low levels. Raw material coal tar market new orders showed mixed gains and losses with unclear directional guidance, creating a certain bearish impact on the carbon black market and loosening cost-side support. Terminal market performance was sluggish, downstream procurement enthusiasm was mediocre, and buyers mostly adopted a wait-and-see approach with only essential follow-up purchases.
2.1 Coal Tar Market Weekly Average Price Analysis
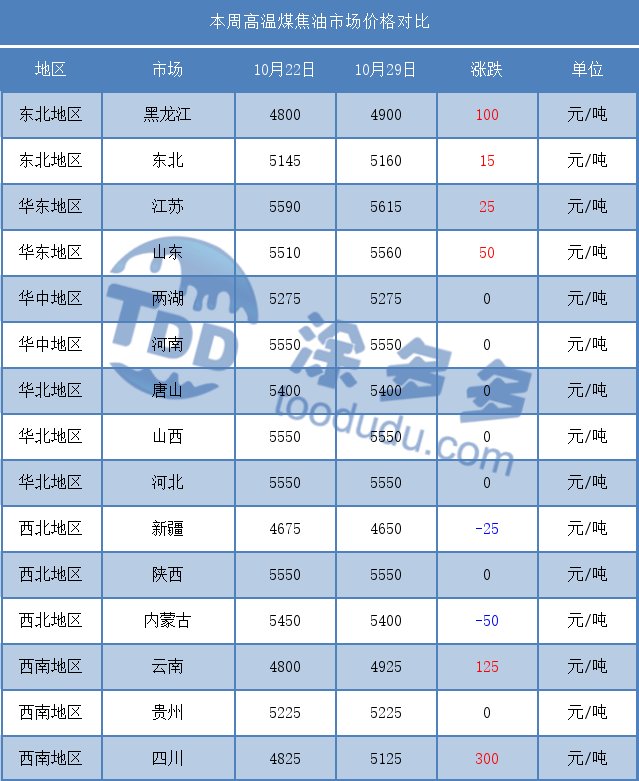
This week, the high-temperature coal tar market showed mixed gains and losses. During the period, the domestic coal tar market maintained a wait-and-see stance for most of the time, with both buyers and sellers exercising caution while awaiting new order guidance. Although coal tar pitch prices experienced some decline, deep-processing products including industrial naphthalene and small oil fractions saw significant price increases in new order auctions, providing clear market support. Under interwoven bullish and bearish factors, the coal tar market saw intensifying long-short interplay. Approaching the weekend, as new order prices were gradually released, some regions showed mixed results while most areas maintained prices stable. In the short term, the coal tar market will continue to see long-short interplay, with prices facing a dilemma and directional breakthrough still awaiting new catalysts.
This week, the domestic anthracene oil market new orders temporarily stabilized, with overall trading atmosphere remaining thin. During the period, raw material high-temperature coal tar prices in main production areas had not yet been tendered, lacking clear directional guidance. Anthracene oil market participants mostly waited for raw material prices to be released before making adjustments, with overall quotes remaining quiet and observant. The downstream carbon black industry maintained a passive market entry stance, with sluggish negotiation atmosphere and slow procurement pace. Anthracene oil market cautious wait-and-see sentiment was strong. Approaching the weekend, raw material high-temperature coal tar market trends showed mixed gains and losses, continuing to provide bearish guidance for anthracene oil, with cost support weakening. Under these conditions, downstream carbon black maintained persistent price-suppression sentiment.
Market Outlook
Looking ahead to next week, coal tar new orders show mixed gains and losses with unclear directional guidance, and the bearish impact on the carbon black market persists. Cost support has loosened, making it difficult to form an effective floor. Terminal market performance remains sluggish, downstream procurement enthusiasm is mediocre with mostly wait-and-see or essential follow-up approaches, and the stalemate negotiation pattern is unlikely to improve in the short term. Overall, with buyers and sellers continuing to compete and new order prices lacking upward momentum, the market is expected to maintain low-level weak consolidation in the short term.
4. Carbon Black Industry N330 Profit Analysis
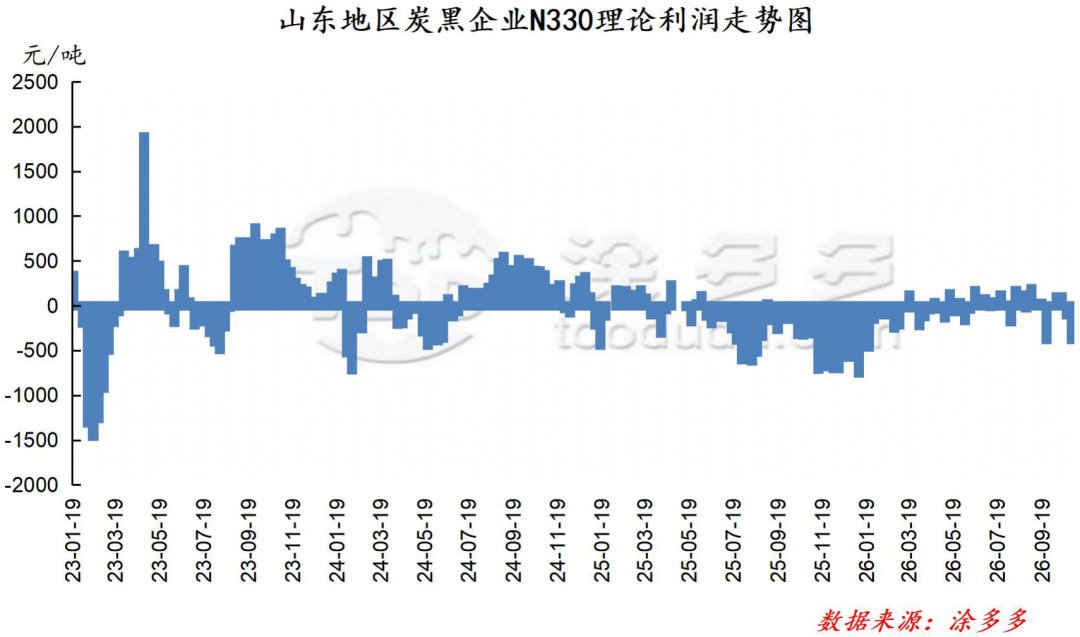
Taking Shandong region as an example, raw material coal tar market new order prices rose narrowly, but carbon black market new order prices declined due to downstream suppression. Theoretically calculated carbon black market profits declined, with the loss amplitude expanding. As of now, the carbon black industry theoretical weekly profit stands at minus 373 yuan/ton, down 277.8 from the previous period.
5. Weekly Market Operating Rate Statistics
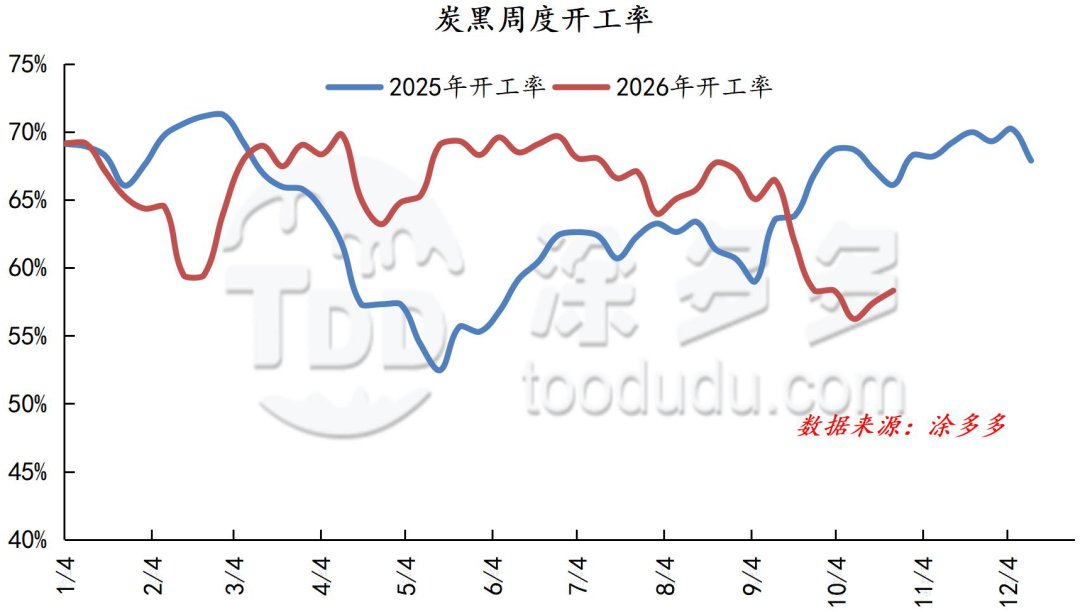
The operating rate for domestic carbon black market sample enterprises was 59%. The operating rate rose narrowly, driven by a manufacturer in Shandong region resuming production, which lifted the regional operating rate. New order shipments remained difficult, and the carbon black market continued under pressure. Currently, manufacturer production enthusiasm is not high, with some large factories maintaining low operating rates. Overall, the carbon black market operating rate increased slightly.
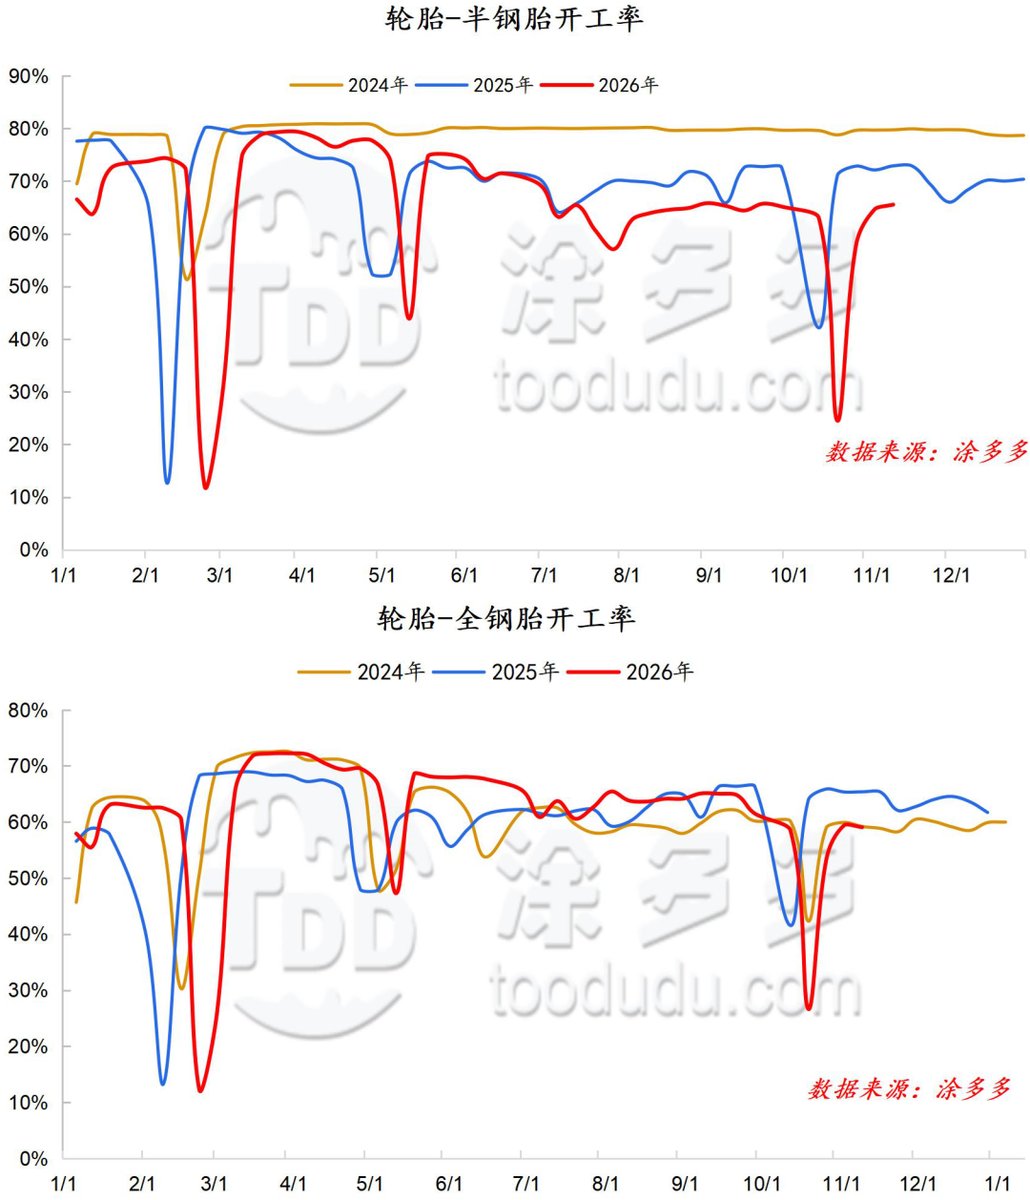
The operating rate for Chinese semi-steel tires was 66%. The operating rate for Chinese all-steel tires was 59%.
Overall operating rates declined slightly week-on-week. As various raw material prices continued to run high, tire enterprises faced significantly increased cost pressure, which suppressed production scheduling. Some enterprises flexibly adjusted operating loads to control costs. In the short term, the high-cost pattern is unlikely to see substantive relief, and operating rates may maintain narrow fluctuations.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
-
Titanium Product Market Quotation(Nov 6)5256
-
Carbon Black Daily Report: Stability on the Surface, Hidden Pressure Beneath(Nov 6)5402
-
Natural Rubber Daily Report: Destocking Provides Temporary Support, Inventory Accumulation Pressures the Outlook(Nov 6)9660
-
Titanium Product Market Quotation(Nov 5)5548
-
Carbon Black Weekly: Calm on the Surface, Competition Beneath(Nov 5)7168