Rubber Special Issue - October 2026
Rubber Special Issue - October 2026
Natural Rubber Market Price Analysis
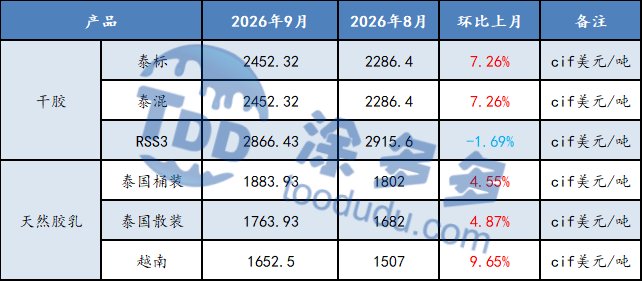
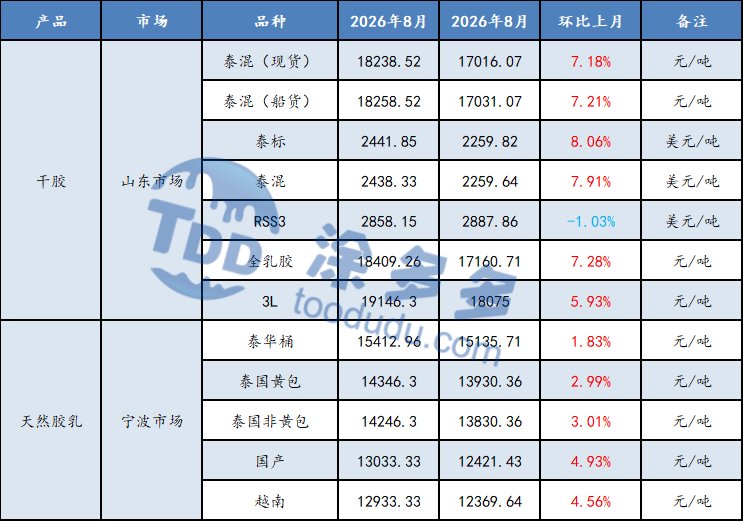
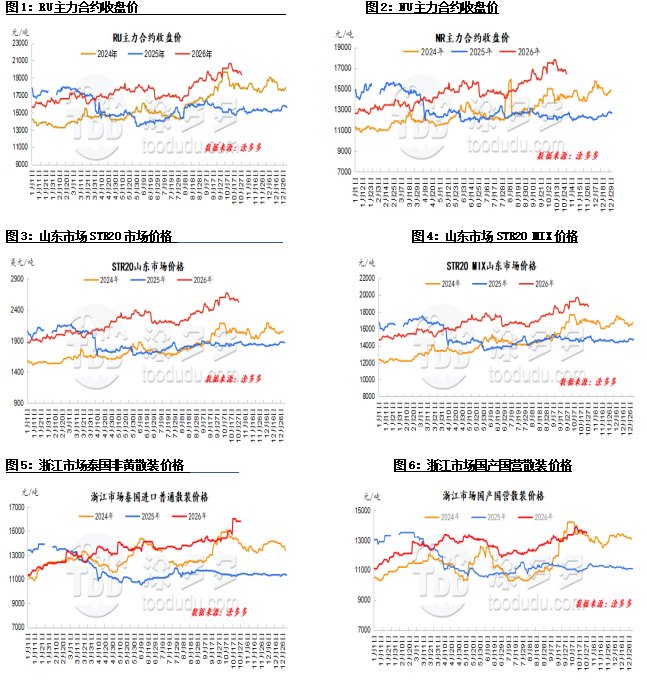
In September, natural rubber dry rubber exhibited an "N"-shaped trend. At the beginning of the month, raw material prices in domestic and international production areas continued their upward trend. Upstream processing factories actively purchased at premiums, spot inventories continued to draw down, and downstream just-in-time demand provided support. Combined with strong crude oil market gains and a broadly positive macro commodity environment, favorable fundamental factors converged, driving rubber prices sharply higher. As prices continued to rise, upstream purchasing enthusiasm cooled, cost support weakened, and downstream buyers adopted a wait-and-see approach with limited just-in-time restocking. Earlier favorable factors gradually became priced in, and rubber prices began to decline. Toward month-end, rainfall in overseas production areas disrupted tapping, once again supporting prices.
Natural Rubber Latex
In September, concentrated latex prices were less volatile than dry rubber. In the first third of the month, the macro commodity environment improved, futures surged to new yearly highs, and uninterrupted rainfall in Southeast Asian production areas disrupted tapping. New rubber supply increased slowly, and raw material and cost prices rose again. Import cost support strengthened continuously, while arrivals at consumption areas remained relatively limited, especially for Thai concentrated latex where spot supply stayed tight. Under multiple favorable factors, traders raised spot quotes successively, and negotiated transaction prices moved higher. However, downstream product manufacturers resisted high-priced raw material restocking, maintaining small-lot just-in-time purchases with existing material reserves.
Market Outlook:
1. In October, global supply is in the peak production season, and cost support is expected to weaken.
2. In October, tire sample enterprise operating rates are expected to decline due to holiday maintenance shutdowns.
3. In October, natural rubber social inventories are still expected to continue drawing down.
Monthly Rubber Market Price Comparison
Rubber Market Price Analysis Charts
Natural Rubber Supply Analysis
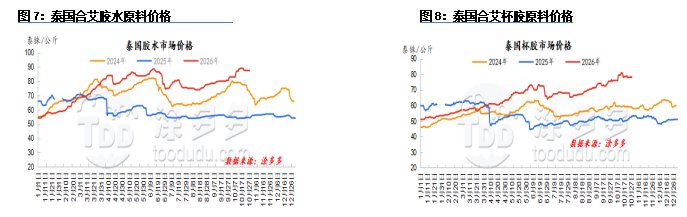
At the beginning of September, rainfall increased in Thai production areas, particularly in the northeastern region, slowing raw material release. Dry rubber factories showed active willingness to purchase at premiums, continuously bidding up raw material prices. Into mid-month, rain continued to affect southern Thailand, keeping latex procurement prices firm. In northeastern Thailand, rainfall decreased month-on-month, and processing factories began to press down cup lump purchase prices, resulting in cup lump gains lagging behind latex. However, by month-end, southern Thailand experienced more rainfall disruption than the northeast, limiting supply increases and keeping latex prices firm. Second-tier traders held back sales and processing factories bid aggressively for cup lumps, causing cup lump price gains to exceed those of latex.
In September, frequent rainfall in Vietnamese production areas significantly disrupted daytime tapping operations, limiting raw material release pace. The precipitation disruption supported raw material prices, and high raw material costs continued to pressure processing factory margins. The rainfall impact persisted until mid-September, after which weather improved, tapping operations gradually recovered, overall output returned to normal levels, and raw material prices fluctuated slightly but remained generally stable, with relatively solid cost support.
Yunnan Production Area
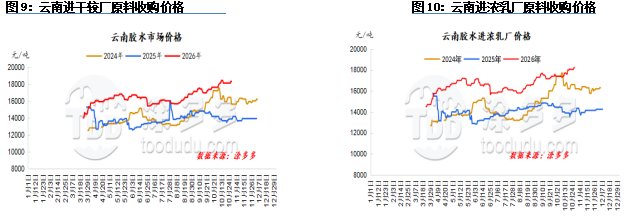
In September, rainfall decreased in the production area, and latex volume was gradually increasing. Some processing factories were reluctant to accept current prices, leading to disorderly market quotes with both high and low prices, though the overall trend remained upward. As spot prices corrected, raw materials ended their upward trend and began declining. Approaching month-end, weather improved and latex volume continued to increase, though overall volume fell short of expectations, particularly for cup lump which remained slow. With the holiday approaching, purchasing strategies varied among processing factories, resulting in both high and low prices in the market.
Hainan Production Area
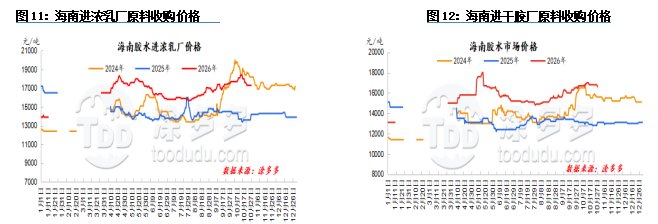
In September, weather conditions improved compared to the previous period, and high prices stimulated farmer enthusiasm for tapping. Island raw materials gradually became available, and new rubber supply showed a month-on-month increasing trend. As futures surged, arbitrage positions increased willingness to add positions, driving increased orders at local concentrated latex processing factories and upward profit margin recovery. Given expectations of continued rainfall disruption in production areas, local processing factories maintained strong production enthusiasm and intensified competitive bidding for raw materials, continuously pushing up raw material purchase prices.
Import and Export
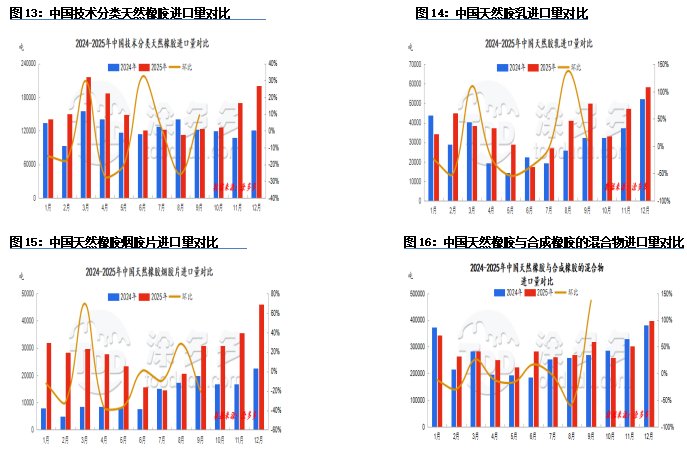
According to customs data, in August 2026, China's natural rubber imports (including technically specified rubber, latex, ribbed smoked sheets, primary shapes, mixed rubber, and compound rubber) totaled 486,000 tons, up 5.96% month-on-month and down 6.68% year-on-year. Cumulative imports for January-August 2026 reached 4.0758 million tons, down 1.11% year-on-year.
August natural rubber exports totaled 16,300 tons, down 15.1% month-on-month and up 173.22% year-on-year. Cumulative exports for January-August 2026 reached 99,400 tons, up 49.85% year-on-year.
Technically Specified Natural Rubber
August 2026 imports of technically specified natural rubber: 103,600 tons, down 25.89% month-on-month and down 8.37% year-on-year.
Natural Rubber Latex
August 2026 natural rubber latex imports: 22,500 tons, up 137.64% month-on-month and down 44.79% year-on-year.
Ribbed Smoked Sheets
August 2026 ribbed smoked sheet imports: 21,500 tons, up 28.22% month-on-month and up 4.08% year-on-year.
Natural and Synthetic Rubber Mixtures
August 2026 imports of natural and synthetic rubber mixtures: 103,600 tons, down 61.40% month-on-month and down 58.51% year-on-year.
Import and Export Trend Chart
Global Rubber Production
The latest ANRPC July 2026 report projects July global natural rubber production to decline 5.2% to 1.321 million tons, up 6.3% from the previous month. Consumption is projected to increase 0.8% to 1.297 million tons, up 0.3% from the previous month. For the first seven months, cumulative global production is projected to decline 2.3% to 7.426 million tons, with cumulative consumption declining 1.6% to 8.759 million tons.
Full-year 2026 global natural rubber production is projected to increase 2.1% year-on-year to 15.279 million tons. By country: Thailand +1.4%, Indonesia -0.8%, China +2.9%, India +4.4%, Vietnam -4.2%, Malaysia +6.9%, Cambodia +2.9%, Myanmar +1.1%, Sri Lanka +12.4%, and non-member countries +5.7%.
Full-year 2026 global natural rubber consumption is projected to increase 0.4% year-on-year to 15.356 million tons. By country: China +1.2%, India +0.2%, Thailand -3.5%, Indonesia +1%, Malaysia +8.2%, Vietnam -5.7%, Sri Lanka -5.1%, Cambodia +7.5%, Philippines +13.8%, and non-member countries -0.1%.
Note: Global natural rubber consumption data is based on the latest available figures and is for reference only.
Natural Rubber Inventory Analysis
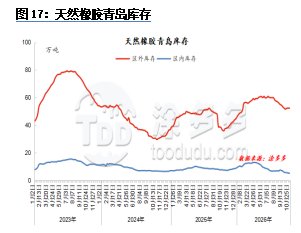
In September, Qingdao natural rubber social inventories maintained their destocking trend. As Southeast Asia gradually entered the peak tapping season, overall warehouse inflows at Qingdao increased. With natural rubber prices continuously hitting highs, downstream enterprises primarily consumed existing inventories. Traders restocked actively and arbitrage positions added to their positions, keeping Qingdao warehouses in an overall destocking state.
Natural Rubber Demand Analysis
In September, the operating rate for Chinese semi-steel tires was 65%, and for all-steel tires was 63%.
Tire enterprise operating rates showed some divergence. Semi-steel tire operating rates recovered as enterprises completed maintenance restarts, but most enterprises remained in production control mode, limiting overall rate increases. For all-steel tires, some enterprises restarted from maintenance, but continuously rising raw material prices caused losses on certain specifications, strengthening enterprises' willingness to control production and dragging operating rates lower. As raw material cost pressures continued to build, semi-steel tire enterprises mostly adopted flexible production scheduling strategies, while some all-steel tire enterprises arranged shutdowns for maintenance. Combined with some enterprises intensifying production limits, industry operating rates entered a clear downward trend.
Monthly Industry News
Wanli Tire IPO Enters Sprint Phase, Plans to Raise 2 Billion Yuan for Overseas Capacity
On September 21, Wanli Tire Co., Ltd. updated its prospectus, moving within steps of listing on the Shenzhen Stock Exchange main board. The company plans to raise 2 billion yuan, focusing on overseas capacity layout and intelligent manufacturing upgrades.
Overseas projects dominate the fundraising allocation. The Malaysia production base is slated for 930 million yuan, the Cambodia project for 180 million yuan, together totaling 1.11 billion yuan and accounting for over half. Remaining funds are allocated for working capital supplementation (400 million yuan), R&D center upgrades (310 million yuan), and Conghua base Phase III expansion (180 million yuan).
Wanli Tire, formerly Guangzhou Hua Nan Rubber Tire Co., Ltd. established in 1988, is now a Guangzhou state-owned enterprise. The company operates three production bases in Conghua (Guangzhou), Hefei (Anhui), and Cambodia, with in-production capacity of 30 million semi-steel tires and 3.2 million all-steel tires. The 2025 capacity utilization rate reached 100.09%, with semi-steel and all-steel tire sales-to-production ratios of 97.49% and 100.40% respectively, creating urgent expansion needs. The Cambodia base commenced production in January 2026, taking only 288 days from groundbreaking to first tire off the line. The Malaysia base, a joint venture with the Berjaya Group, involves total investment of approximately 320 million USD.
In terms of performance, revenue grew from 5.588 billion yuan in 2023 to 7.028 billion yuan in 2025, a CAGR of 12.14%. Net profit increased from 398 million yuan to 419 million yuan. Overseas revenue accounts for over half, with declining revenue from the US and Mexican markets offset by significant growth in emerging markets such as Brazil, Saudi Arabia, and the UAE.
The company's "Wanli Tire 5G Factory" is one of the first three 5G factories in the rubber industry, with 369 cumulative patents and R&D investment maintaining approximately 4% of revenue over the past three years. Through this IPO, Wanli Tire is accelerating its "China R&D + Southeast Asia manufacturing + global sales" operational framework.
Lei Jun Visits XCMG Giant Mining Tire, Michelin Custom Giant Tire Unexpectedly Goes Viral
On September 12, Xiaomi Auto's Pengcheng series range-extended SUV held its first delivery ceremony in Xuzhou, Jiangsu. Xiaomi Group Chairman and CEO Lei Jun personally handed keys to 20 owners. After the ceremony, Lei Jun visited XCMG Group's mining machinery division, where he not only operated a large mining excavator but also took photos with a giant mining tire. The enormous tire created a striking visual contrast with Lei Jun, quickly going viral online.
The tire came from global tire giant Michelin, custom-developed for XCMG as an exclusive specification product. As a core component of mining heavy trucks, the giant tire is designed for open-pit mines, rugged mining areas, and other extreme working conditions. It must withstand hundreds of tons of vehicle and material weight, endure high-intensity crushing, gravel impact, and extreme temperature environments, requiring the highest standards in material formulation, structural design, and wear resistance. For reference, the world's largest specification all-steel giant tire exceeds 4 meters in outer diameter, can weigh over 5 tons per tire, and costs hundreds of thousands of yuan per unit.
Michelin and XCMG have a long-standing partnership. Michelin was the first tire supplier for XCMG all-terrain cranes, officially becoming a supplier for XCMG large loaders in 2013, later upgraded to a global long-term strategic partner. In the passenger car sector, Michelin is also deeply aligned with Xiaomi Auto, providing e-Primacy low-rolling-resistance tires and PilotSport EV silent sport tires as original equipment for the SU7 and YU7.
Industry observers note that Lei Jun's visit, while seemingly casual, reflects the deep integration of China's manufacturing supply chain. Xiaomi representing intelligent new energy vehicles, XCMG representing high-end heavy equipment, and Michelin representing the international tire giant are forming a full-scenario supporting ecosystem in the Chinese market, from passenger car tires to mining giant tires. As China's new energy and heavy equipment industries accelerate, how tire companies position themselves simultaneously in high-performance passenger car tires and specialty giant tires while deepening strategic partnerships with leading OEMs will become a key competitive focus.
Dunlop Exits Karting Tire Business, Officially Terminating by End of 2027
On September 4, Sumitomo Rubber Industries announced that based on medium-to-long-term business strategy and resource allocation reassessment, its Dunlop brand will exit the karting tire business, with existing customer supply continuing through December 31, 2027.
Dunlop has supplied karting tires since 1976, spanning over 50 years. Products covered recreational driving and youth racing segments, including competition models certified by CIK-FIA and Japan JAF. Sumitomo Rubber stated the decision resulted from reviewing business direction and resource allocation, with future resources directed toward premium motorsport and passenger car tire segments. While the company has not disclosed specific reasons for discontinuation, the limited market size of karting tires and the need for continuous R&D and motorsport support investment are background factors for the resource adjustment.
For domestic karting clubs, youth training programs, and spare tire channels, normal procurement remains available through end-2027.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
-
Titanium Product Market Quotation(Nov 6)5256
-
Carbon Black Daily Report: Stability on the Surface, Hidden Pressure Beneath(Nov 6)5402
-
Natural Rubber Daily Report: Destocking Provides Temporary Support, Inventory Accumulation Pressures the Outlook(Nov 6)9660
-
Titanium Product Market Quotation(Nov 5)5548
-
Carbon Black Weekly: Calm on the Surface, Competition Beneath(Nov 5)7168